For a growing number of Nigerian founders and professionals, the question is no longer whether to hold wealth outside the naira, but how to do it properly. The naira has lost most of its dollar value since 2023, and even those who saved diligently in domiciliary accounts discovered an uncomfortable truth: holding dollars inside a Nigerian bank is not the same as having free access to them.
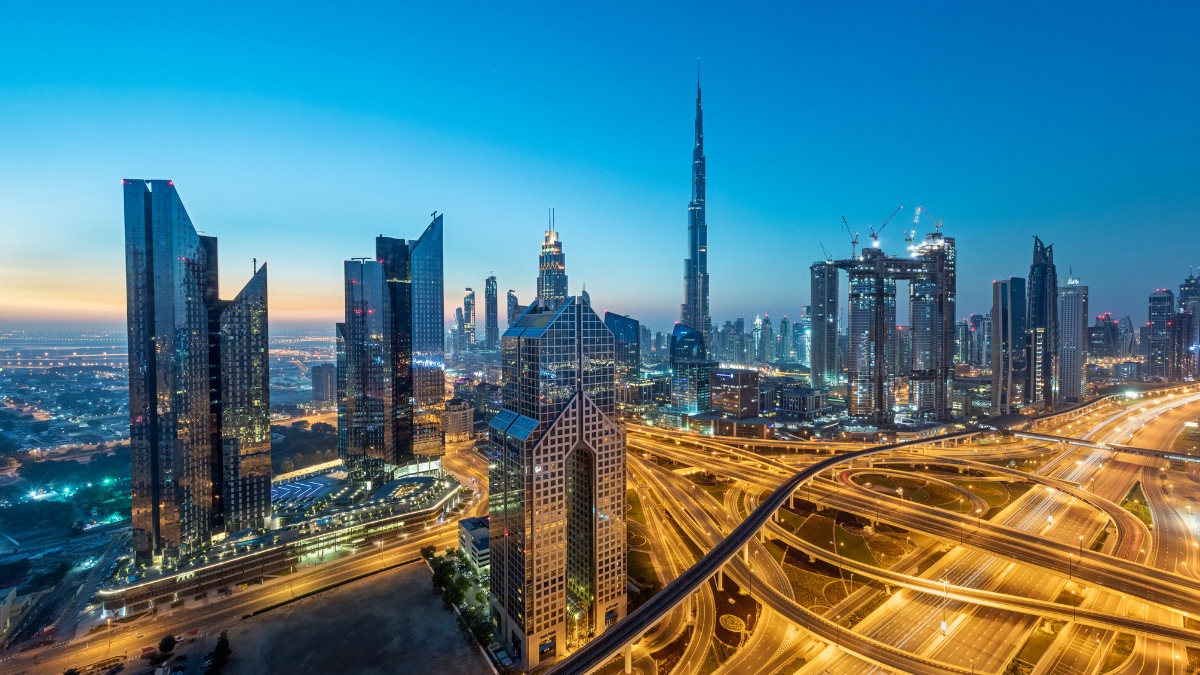
Dubai has become the default answer for many. It is a four-hour daily-flight corridor from Lagos and Abuja, home to a large and successful Nigerian business community, and offers zero personal income tax, dollar-pegged stability, and company formation measured in days rather than months.
But "move money to Dubai" covers several very different strategies, and the forex rules on the Nigerian side matter as much as the opportunities on the Emirati side. This guide sets out the options clearly. It is general information, not financial, tax, legal or investment advice; Nigerian forex regulation changes frequently, and you should take professional advice on your specific situation before moving anything.
The Nigerian side: what the rules actually allow
Unlike South Africa, Nigeria has no fixed annual "offshore allowance." What you can move, and how, depends on the source of your funds and the documentation behind them.
Domiciliary accounts remain the backbone. Foreign currency you have legitimately earned or received (salary in dollars, export proceeds, diaspora remittances, inheritance) can be held in a domiciliary account and, under the CBN's Foreign Exchange Manual (Fourth Edition, effective 1 June 2026) — read alongside the Nigeria Foreign Exchange (FX) Code that took effect in December 2024 — transferred abroad with fewer restrictions than during the 2020 to 2024 clampdown era. The direction of travel is liberalisation, but documentation, source-of-funds evidence and bank compliance checks are non-negotiable, and processing can still be slow.
Buying forex through official channels is documented, not unlimited. Transfers for investment, education, medical and travel purposes go through authorised dealer banks with supporting paperwork. Since the exchange rate unification, the gap between official and parallel rates has narrowed, which has made official channels far more usable than they were.
The parallel market is not a shortcut worth taking. Undocumented transfers through informal channels create exactly the problem you are trying to escape: money that cannot be explained to a UAE bank. Emirati banks apply serious source-of-funds scrutiny to Nigerian applicants, and clean, traceable money is the single biggest determinant of whether your UAE account opens smoothly. Funds that arrive through informal routes can be unbankable at the destination, whatever their origin.
The practical takeaway: the constraint for most Nigerians is not a legal ceiling, it is documentation. Plan the paper trail before you plan the transfer.
Option 1: A UAE company that earns in hard currency
For Nigerian business owners, this is usually the most powerful option, because it sidesteps the transfer problem entirely. Instead of moving naira out, you build an income stream that earns dollars or dirhams from day one.
A Dubai or Abu Dhabi Free Zone company gives you 100 percent foreign ownership, a trade licence typically issued within a week, tier-one banking access, and residence visas for you and your family. For Nigerians in import-export, logistics, tech, consulting, oil and gas services or e-commerce, the structure lets you invoice international clients in hard currency, hold profits offshore, and use Dubai's trade infrastructure between Africa, Asia and Europe.
Pros. No large capital lump sum needs to leave Nigeria; setup starts from a few thousand dollars. Hard-currency revenue accrues offshore. A UAE residence visa comes with the package, which also removes the tourist-visa uncertainty Nigerian passport holders have faced in recent years, since entry rules for Nigerians have shifted several times and a residence permit puts you on a different footing altogether. The entire setup can be done remotely from Lagos or Abuja.
Cons. A UAE company is not a tax vanishing act. Nigerian tax residents are taxed on worldwide income, and recent Nigerian tax reforms have sharpened the rules around foreign income and residency. A company managed entirely from Nigeria can create Nigerian tax exposure regardless of where it is registered. The structure works best with genuine international activity and proper advice on both sides.
Who it suits. Founders with international clients or trade flows, which describes a large share of the Nigerian businesses already operating between Lagos and Dubai.
Option 2: Dubai property
Nigerians have consistently ranked among the most active African buyers of Dubai real estate. The appeal: gross rental yields of 5 to 8 percent, no local income, capital gains or annual property taxes, dollar-pegged pricing, and a 10-year Golden Visa for property holdings of AED 2 million or more, with staged developer payment plans that can match the pace at which funds can be moved.
Pros. A hard, income-producing dollar asset with long-term residency attached, in a city with deep Nigerian community ties.
Cons. Concentration risk in one cyclical market, roughly 4 percent transfer fees, service charges that erode net yield, developer risk on off-plan purchases, and slow exits in downturns. Source-of-funds scrutiny applies in full to property purchases. UAE succession rules also differ from what Nigerian buyers expect, so a DIFC will or equivalent estate structure is essential. And while you remain a Nigerian tax resident, the rental income is taxable in Nigeria.
Who it suits. Investors who want a tangible asset plus the Golden Visa, buying with documented funds they will not need back quickly.
Option 3: An offshore investment portfolio
The least glamorous option and often the most sensible foundation: a globally diversified portfolio held on an international platform, funded from your domiciliary account or offshore earnings.
Pros. Genuine diversification across markets and currencies, daily liquidity, low costs, and no single-asset or single-city risk.
Cons. No residency benefit, no yield story to tell at dinner, and the same Nigerian tax exposure on income and gains while you remain resident.
Who it suits. Anyone whose primary goal is simply protecting wealth from naira depreciation before pursuing anything more structural.
Option 4: The full relocation
Some Nigerian families take the complete step: relocating, obtaining UAE residency through business or property, and restructuring their affairs so that little or no Nigerian tax residency remains. At that point the UAE's zero personal income tax genuinely applies.
This is a serious legal and life decision, not a paperwork exercise. Nigerian residency rules look at physical presence and ties, the family typically needs to genuinely move, and the costs of Dubai schooling, housing and healthcare are real. Done properly, with advice, it is transformative for high earners; done casually, it creates tax exposure in two countries.
Common mistakes Nigerians make on this journey
Funding a UAE company or property through informal transfer channels, then failing UAE bank compliance because the money cannot be traced.
Assuming a Free Zone licence alone eliminates Nigerian tax. Management and control from Nigeria can pull the company back into the Nigerian tax net.
Buying off-plan property from a roadshow without independent checks on the developer, escrow status and completion risk.
Ignoring the estate planning gap between Nigerian expectations and UAE succession law.
Leaving document legalisation too late. Attestation of Nigerian corporate and personal documents for UAE use takes time; start early.
The bottom line
For Nigerians, the smartest move is usually not "getting money out" but building structures that earn and hold value in hard currency legitimately: a UAE company for the business, documented transfers for investments, and property or the Golden Visa where residency optionality matters. Every one of these works, and every one of them fails if the paper trail is weak. Start with clean documentation, sequence the steps properly, and get advice on the Nigerian tax position before the first dirham moves.
Frequently Asked Questions
Can Nigerians legally move money to Dubai?
Yes, through documented channels: domiciliary account transfers, authorised dealer banks, and legitimately earned offshore income. The constraint is documentation and source-of-funds evidence, not a fixed annual limit. Informal parallel-market transfers create compliance problems at both ends.
How much does it cost to open a company in Dubai from Nigeria?
Free Zone setup packages typically start from a few thousand US dollars, with a licence issued in days and an investor residence visa available as part of the package. The process can be completed remotely.
Do Nigerians need a visa to run a Dubai company?
You can own a UAE company without living there. Most founders take the investor residence visa that comes with formation, which also simplifies travel, banking and family sponsorship.
Can Nigerians get the Dubai Golden Visa?
Yes. The main routes are property holdings of AED 2 million or more, business investment, or qualifying professional and talent categories. Nationality is not a barrier; documentation and source of funds are the tests that matter.
Will I still pay Nigerian tax on Dubai income?
While you remain a Nigerian tax resident, Nigeria taxes your worldwide income, including Dubai rental income and, depending on structure and management, company profits. The UAE's zero personal tax only fully benefits those who properly cease Nigerian tax residency. Take advice before assuming otherwise.
Sources
- Foreign Exchange Manual (4th Edition, 2026) — CBN reforms — Central Bank of Nigeria
- Nigeria Foreign Exchange (FX) Code — Central Bank of Nigeria
- UAE Golden Visa — official portal — The Official Portal of the UAE Government
- UAE corporate tax — UAE Federal Tax Authority